

BasicsGridOntario Power Generation poured first nuclear concrete for its 300 MWe BWRX-300 at Darlington on June 26, 2026, according to the World Nuclear Association. Commercial operation is targeted for 2030. In 2019, GE Hitachi had said construction could start in 2024 or 2025 with operation in 2027 or 2028. The start date held. The finish moved.
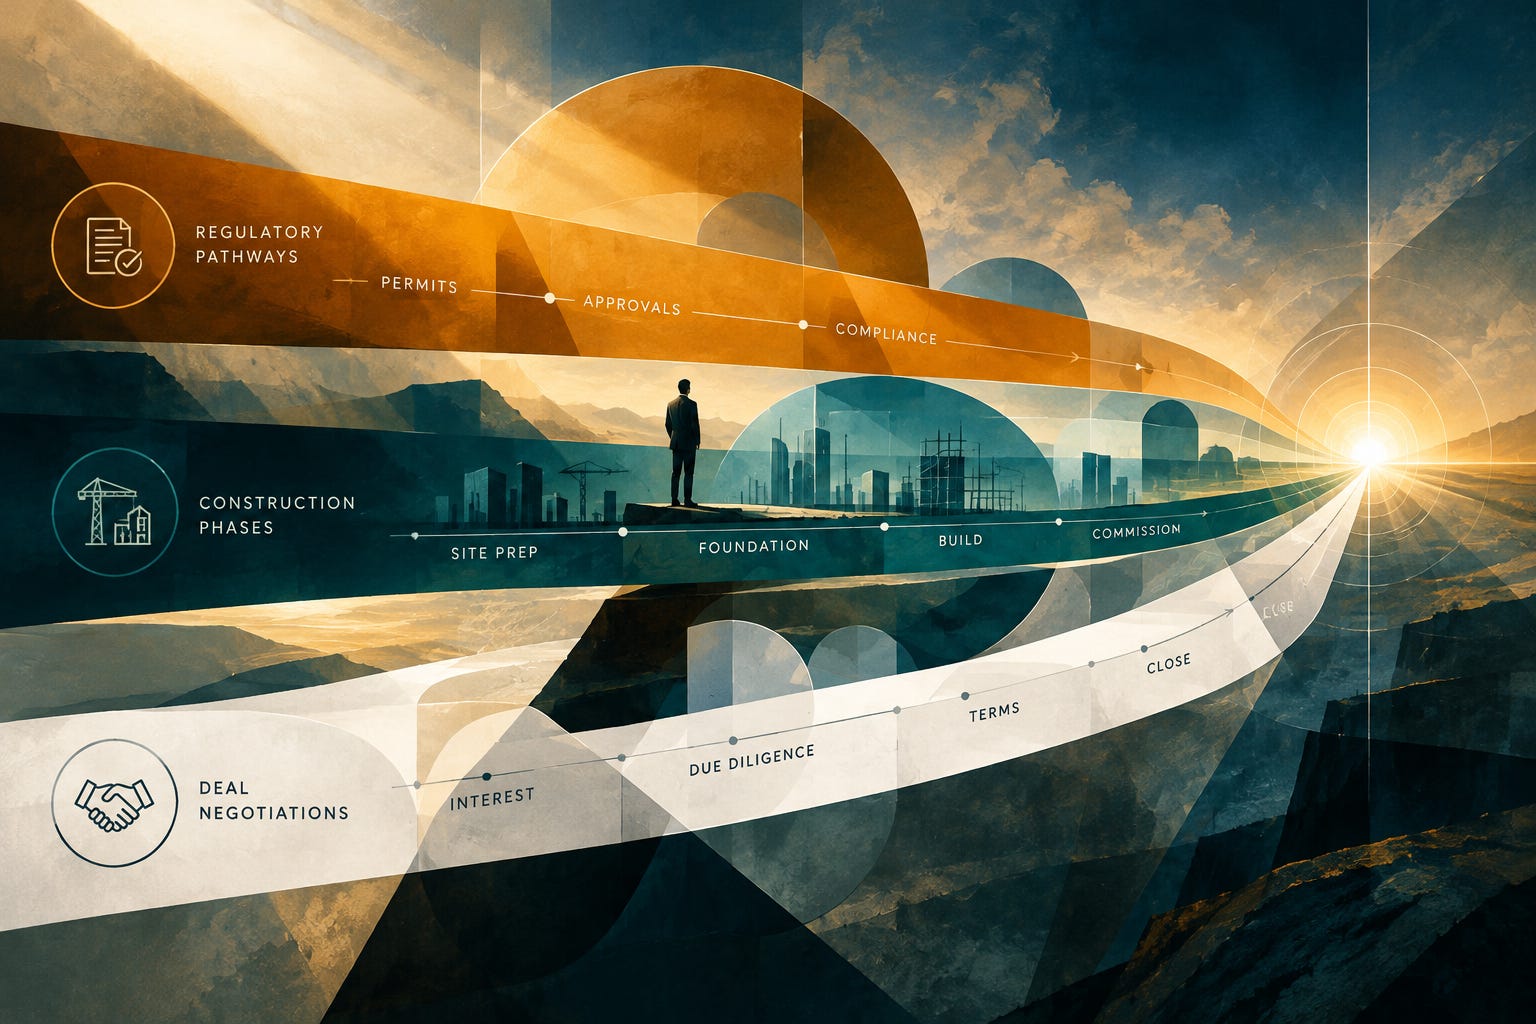
That gap is the real answer to the timeline question. For a Western first-of-a-kind SMR, the evidence supports eight to ten years from technology selection to commercial operation. Construction is roughly three to four of those years. Licensing is the shortest leg, and the part nobody can compress yet is the deal that sits between the permit and the first pour.
Licensing is now the shortest leg
The NRC has cut its own clock. TVA’s Clinch River application reached a construction permit on September 29 after a 14-month review. TerraPower’s Natrium review, set at 27 months, finished in 18 months, and the permit followed on March 4, 2026. Executive Order 14300 sets an 18-month target for these reviews.
Counting from the application hides the earlier years. TVA received its early site permit in 2019, so the full road to a Clinch River permit took about seven years. Dow’s Long Mott project, four Xe-100 modules in Texas, shows a case still in progress. The NRC finished its environmental review in under a year, and the final safety evaluation is targeted for November 2026. A licensing board also admitted a contention from Waterkeeper in January, a reminder that a fast review is not a guaranteed one.
The UK runs a slower clock. The Office for Nuclear Regulation’s Generic Design Assessment of the Rolls-Royce SMR began in April 2022 and is expected to conclude by December 2026. That is nearly five years, and it covers the generic design only, not any site.
The deal clock has not shortened
Money moves slower than regulators. The RoPower project in Romania, six 77 MWe NuScale modules totaling 462 MWe, began with a memorandum of understanding in March 2019. Nuclearelectrica’s shareholders approved a final investment decision on February 12, 2026, seven years later. The Romanian energy ministry has estimated the budget at EUR 4.9 billion. POWER reported that the conditions attached to the decision are unpublished. This week, Romanian outlet Mediafax reported that Nuclearelectrica’s chief executive is pressing NuScale for firm commitments so Romania does not carry the risk disproportionately.
Wylfa shows the same pattern in the UK. Great British Energy - Nuclear and Rolls-Royce SMR signed a contract on April 13 for three 470 MWe units, backed by a GBP 599 million National Wealth Fund facility. The contract covers site-specific design. The final investment decision is expected in 2029, with grid power in the mid-2030s.
Darlington moved fastest because the owner is a provincial utility. Ontario approved the C$20.9 billion budget in May 2025, within weeks of the construction licence. The lesson is simple. The deal clock tracks the owner’s balance sheet, not the reactor design.
Construction: define the start before you count the months
Developers do not agree on what “construction start” means, and the choice shifts schedules by a year or more. A short rundown:
Darlington BWRX-300 (300 MWe): licence to construct in April 2025, a 953-tonne basemat module set in April 2026, first nuclear concrete June 26, 2026, commercial operation targeted for 2030. GE Vernova Hitachi says later units could be ready for fuel in 24 to 36 months from first nuclear concrete.
TerraPower Natrium (345 MWe sodium-cooled fast reactor): non-nuclear work began in June 2024 and nuclear construction on April 23, 2026. TerraPower told POWER the first unit is on a 38-month schedule from nuclear concrete to fuel loading, and 36 months for later units. Completion is targeted for 2030.
Linglong One (125 MWe, China): construction began July 13, 2021. A tracker showed no confirmed first criticality as of July 10, 2026. For comparison, the 1,100 MWe Hualong One unit Changjiang 3 began in March 2021 and connected to the grid on August 1, 2026.
That last pairing is the sobering one. Even in China, a small first-of-a-kind unit has not built faster than a large unit in a serial program. If you are tracking the nuclear market professionally, SMRbrief Pro gives you the structured database to go deeper than any single article can.
Hold points matter too. Darlington cleared its first in late March. The next one is reactor pressure vessel installation. Nuclear Newswire also reported that construction began with an incomplete design, which is common at this stage and carries schedule risk.
Slippage is the base case
Take any announced schedule and ask what has already moved. Kairos Power set a 2027 operating target for Hermes 1, its non-power demonstration reactor, when it began nuclear construction in May 2025. The Venture Atlas profile reports that in May 2026 the NRC extended the construction-completion deadline by 28 months to April 30, 2029, and that Kairos now expects to finish building in 2028. Darlington’s completion also slid a year, because the CNSC licence arrived later than OPG expected, as the Globe and Mail reported.
Developers say the same thing in their filings. X-energy’s latest 10-Q states that its cost and schedule estimates carry significant uncertainty and notes the industry’s history of overruns and delays on first-of-a-kind projects. That is a legal disclosure, but it is also a fair forecast.
A planning range for a first-of-a-kind SMR
The following is our estimate, built from the dated projects above. Five clocks run, partly in parallel, and the longest one sets the date:
Design maturity and pre-application: two to five years or more, and often hidden before the application date.
Licensing, application to permit: 14 to 24 months at today’s NRC.
Deal and financing: anywhere from weeks for a state-backed owner to seven years at RoPower.
Construction, first nuclear concrete to fuel-ready: about three to four years for first units, with vendors claiming 24 to 36 months later.
Operating licence and commissioning: runs alongside construction, as OPG’s March 2026 application shows, but TVA still needs a separate operating licence.
Darlington, the best case, runs from technology selection in December 2021 to commercial operation in 2030, about eight and a half years. Wylfa points to about ten. Second and later units may land closer to five or six years, but no one has built one yet.
Take the last SMR schedule you read and mark which of the five clocks it assumes has already started. Which date in it is contracted, and which one is a hope?